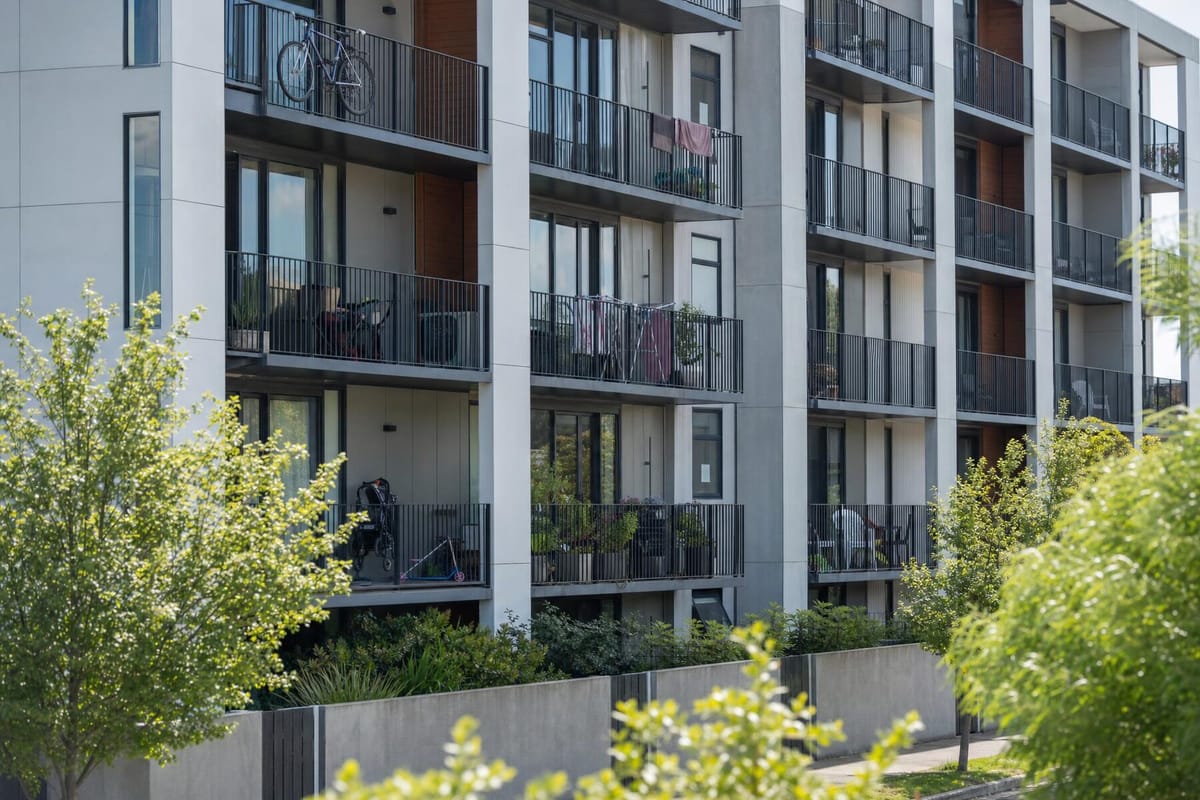
If you are looking at New Zealand’s investor visa, the government announced something on 8 September that will matter to a small number of people and be misread by a good many more. From December, build to rent housing becomes an acceptable investment under the Active Investor Plus Growth category.
Here is the short version before the detail, because the detail changes what most people assume.
You will be able to count purpose-built rental housing towards the Growth category, but only through an approved managed fund, not by building anything yourself. You will not be allowed to live in it. And the rules that would let anyone actually plan around this do not exist yet.
What was actually announced
Three ministers put it out on 8 September, Erica Stanford for immigration, Chris Bishop for housing and Simon Watts for building and construction, and Immigration New Zealand posted it to its news centre the following day (Immigration New Zealand · build to rent added to Active Investor Plus).
The substance is four lines long. Eligible build to rent developments become an acceptable investment under the Growth category from December 2026. Access is through approved managed funds. Those funds have to satisfy requirements around capability, governance and delivery. Further detail on eligibility, structures and timing is promised before December.
That is genuinely all of it. The rest of what has been written about it since is interpretation, mine included.
Funds only, and that is the part people will get wrong
The Growth category normally lets you put money directly into a New Zealand business. That is the whole character of it, and it is why I wrote in August about the approved direct investment list going public again: a Growth applicant is choosing between backing a company and buying units in a fund.
Build to rent does not work that way. The announcement is explicit that it comes through approved managed funds, and the government’s own release says direct investment is not available for it (Beehive · AIP Visa Growth Category expands to support Build to Rent).
So if you are a developer reading the headline and picturing your own project qualifying, that is not what has been announced. You are buying into a fund that someone else has taken through an approval process. If building is the thing you want to do in New Zealand, that is a different conversation and closer to the ground I covered in running a business across the Tasman.
You cannot live in it
Worth stating plainly, because it is the second question everybody asks. Applicants and their family members will not be able to live in a build to rent development funded through their investment.
It is not a housing plan. It is an investment that happens to be housing.
What changed is the tier, not the asset class
This is the bit I have not seen said out loud, and it is the part that would actually shape my advice.
Property was already inside Active Investor Plus. It sits in the Balanced category, which lists new residential, commercial and industrial developments among its acceptable investments, and asks for NZD $10 million held for 60 months with at least 105 days spent in New Zealand (Immigration New Zealand · Active Investor Plus visa).
The Growth category asks for NZD $5 million over 36 months and at least 21 days in the country.
So residential development was already reachable. What is new is that a version of it now reaches the cheaper, shorter, lighter-touch tier for the first time. Half the money, half the term, a fifth of the days on the ground. If you had looked at Balanced purely to get property into the mix and walked away from the ten million, this is the announcement that reopens that file.
I would not overstate it. It is one option among several inside a category that already had options, and it arrives wrapped in a fund structure that will carry its own fees and its own risk. But the tier shift is the real news, and it is not what the headlines are leading with.
What nobody can tell you yet
The eligibility requirements are not published. The investment structures are not published. The implementation timing beyond “December” is not published. Which funds will be approved is, self-evidently, not known.
I am saying that clearly because the gap between an announcement and a set of instructions is exactly where people get sold things. If someone offers you a build to rent Active Investor Plus package in the next few weeks, they are ahead of the rules, and so is anyone quoting you a minimum, a return or a timeline for it. You apply under instructions, not under press releases.
What I would actually do
If you are mid-application under Growth, nothing changes for you right now. Your investment plan was assessed against the instructions in force, and a December option does not disturb it.
If you have been sitting on the decision, do not restructure around this yet. Keep doing the work that will be needed whatever you invest in, which is the source of funds file. Where the money came from, how it moved, and whether the paper trail survives someone reading it closely. That is the part of an investor application that fails, far more often than the choice of asset.
Then watch for the instructions in November or early December, and pick with the actual rules in front of you.
Who this is not for
Most people who write to me about New Zealand are not investor visa candidates, and there is nothing wrong with that. If you are moving for work, the work visa routes and the points-tested residence pathways are the real conversation, and none of them ask you for five million dollars.
For the small number of people this does fit, it is a genuine widening of the choice, and December is soon enough to be worth watching rather than acting on.
If you want to talk it through, the residence side of my practice is where this sits. I will tell you honestly if this is not your pathway, before any money changes hands.